Can Tokenisation Transform the Economics of Infrastructure Finance?
A solar park in northern Germany has completed a digital securities fundraising phase, while Hong Kong has raised approximately HK$20 billion through its latest government digital green bond issuance. Both use blockchain-based financial infrastructure, although they operate at very different scales and serve different purposes. One is associated with a specific renewable-energy development; the other finances eligible environmental projects through sovereign borrowing.
Digital securities could make capital easier to raise, simplify investment administration and allow more investors to participate in infrastructure projects that generate revenue over many years. The technology is already operating in regulated financial markets, supported by established banks, custodians and securities platforms. Whether those arrangements can consistently improve the economics of financing roads, railways, energy installations and utilities remains less certain, particularly where the underlying assets carry substantial construction and operating risks.
Briefing
- Research published by the European Central Bank in April 2026 found borrowing spreads averaging 0.14 percentage points lower for tokenised bonds in a matched sample, but no demonstrated reduction in operational costs.
- Hong Kong’s digital green bond programme expanded from HK$800 million in 2023 to approximately HK$20 billion in September 2026.
- Germany’s Ratekau solar park has completed a tokenised securities fundraising phase associated with a financing structure of up to €6.2 million.
- Smaller investment denominations could broaden participation, although research suggests retail-accessible tokenised bonds do not necessarily offer better liquidity.
- Securities regulation, construction risk, contractual obligations and investor protection remain essential regardless of how an investment is recorded.
How Tokenised Structures Work
Infrastructure finance has traditionally relied on combinations of sponsor equity, commercial bank lending, institutional investment, government funding and bonds issued by public authorities or project companies. The arrangements vary considerably between a motorway concession financed against future toll receipts, a regulated electricity network and a municipal water treatment plant.
Lenders and investors examine how each project will generate revenue, who is responsible for constructing and operating it, and what happens if costs increase or anticipated income fails to materialise. These considerations determine the financing structure, contractual protections and returns required by those providing capital.
Tokenisation introduces an alternative way of representing and administering financial interests within these arrangements. A token is a digital representation of an asset or entitlement recorded on a distributed ledger, commonly described as a blockchain. Depending on its legal structure, it might represent a debt security issued by a project company, an ownership interest in an investment vehicle or a contractual claim to specified payments.
A developer building a €50 million solar installation could, for example, raise part of its capital through digitally represented bonds. Investors would purchase securities carrying defined rights to interest and repayment, while a distributed ledger would record ownership and transfers. Those tokens would not automatically give investors direct ownership of the solar panels, land or electricity revenues, as their rights would depend on the issuing entity, investment documentation and applicable law.
Conventional securities involve several organisations responsible for issuance, custody, settlement, recordkeeping and payment administration. Distributed ledger technology could allow authorised participants to maintain synchronised records, automate certain transactions and reduce duplication between financial intermediaries.
The International Monetary Fund’s examination of tokenisation and financial market inefficiencies explored potential improvements in transaction processing and financial intermediation, while recognising that existing frictions could persist or take new forms. Establishing and operating a digital securities platform also introduces expenses involving technology, cybersecurity, legal structuring and compliance, which must be recovered before the arrangement offers an economic advantage.
Evidence From the Bond Market
The technology has been tested in regulated capital markets for several years. In August 2018, the World Bank launched bond-i, a two-year blockchain-operated bond that raised A$110 million. Developed with the Commonwealth Bank of Australia, the instrument demonstrated that a conventional institutional bond could be created, allocated, transferred and managed using distributed ledger technology.
The investors included established financial institutions, while the transaction remained subject to conventional financial obligations. The World Bank’s Treasury records the issuance as an early milestone in digital securities development.
Hong Kong subsequently established a recurring programme of digital green bonds, beginning with an HK$800 million issuance in February 2023 and expanding to approximately HK$6 billion in February 2024. A third offering in November 2025 reached approximately HK$10 billion, introducing further settlement arrangements involving tokenised central bank money.
The fourth issuance, announced on 29 September 2026, doubled that amount to approximately HK$20 billion across Hong Kong dollar, renminbi, US dollar and euro tranches. Subscription ratios ranged from 1.3 to 11.3 times across the four currencies.
According to the Hong Kong Monetary Authority, the latest transaction used HSBC’s Orion digital assets platform, with clearing and settlement through the Central Moneymarkets Unit. Major international banks participated, including HSBC, J.P. Morgan, BNP Paribas, Standard Chartered, Barclays and UBS, alongside established legal advisers and securities infrastructure providers.
The proceeds are intended to finance or refinance eligible expenditure under Hong Kong’s government green bond framework. This can include environmental and infrastructure-related projects, although bondholders own government debt rather than direct financial interests in individual facilities. The programme demonstrates how blockchain technology is being incorporated into conventional capital markets while retaining the financial institutions and legal disciplines that support traditional bond issuance.
In April 2026, researchers writing in the European Central Bank’s Macroprudential Bulletin published Tokenised Bonds: Assessing Efficiency and Liquidity in a Nascent Market. They assembled a dataset of 183 tokenised bonds and compared selected instruments with conventional securities. Their borrowing-cost analysis used 23 tokenised bonds and 49 conventional bonds, producing 58 matched comparisons.
Tokenised bonds carried yield spreads averaging 0.14 percentage points below those of comparable conventional bonds, equivalent to an approximately 40% reduction in the spread measured against the selected benchmark. The research also found evidence of improved secondary-market liquidity within the matched sample.
The results were less encouraging when it came to issuing costs. Underwriting fees for tokenised bonds averaged 0.04 percentage points, or four basis points, higher than those for conventional securities. Although the difference was not statistically significant, the researchers found no visible reduction in operational costs.
The borrowing-cost result also requires qualification. When alternative benchmark interest rates were applied, the estimated effect lost statistical significance. The matched sample was relatively small, and borrowing costs may have been influenced by issuer characteristics, investor demand or interest in the technology itself.
A 14-basis-point reduction could produce meaningful savings for a large borrower, but the observed difference cannot simply be transferred to a solar project company or a privately financed motorway. Their credit characteristics, financing structures and investor bases differ substantially from those of the issuers examined in the study.
The research provides evidence that tokenised bonds can obtain favourable pricing in particular circumstances, while offering much less support for the assumption that replacing conventional securities infrastructure automatically reduces the expense of raising capital.
Financing Real Infrastructure
Renewable energy offers a practical setting for examining tokenised investment because the underlying assets can be identified, measured and assessed against operating forecasts. A completed solar installation generates electricity that can be recorded against expected production, with revenue potentially coming from power purchase agreements, market sales or other commercial arrangements. Equipment performance and operating expenditure can also be monitored throughout the project’s life.
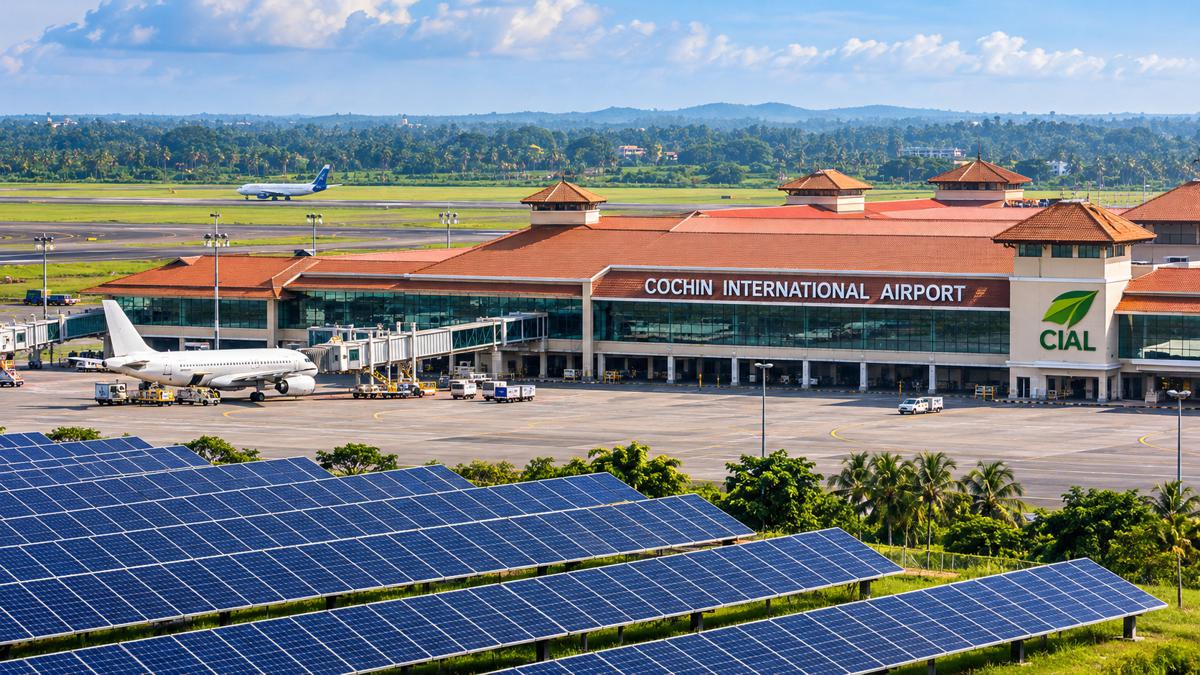
Germany’s Ratekau solar park provides an example of how digital securities are being applied to this type of asset. The development in Schleswig-Holstein has approximately 4.13 MWp of planned photovoltaic capacity, alongside an arrangement for access to battery energy storage. The battery is intended to provide additional flexibility for electricity marketing, although the financing documentation allows it to be owned by a third party and made available to the project through a contractual usage agreement.
In April 2026, financial technology companies Cashlink, FINEXITY and Tangany announced a tokenised securities initiative involving the development. Their initial announcement described a planned issuance of up to €3 million, with total project investment estimated at approximately €5.7 million to €5.8 million, including bank financing. It also projected annual electricity generation of approximately 4.27 GWh.
Subsequent securities documentation dated 3 June 2026 describes a revised financing structure. The Hamburg-based issuer, Green Vision Two GmbH & Co. KG, set out plans to raise up to €6.2 million through three equally ranking tokenised bond offerings, designated Retail, Junior and Advanced, without using other financial borrowings to meet the specified financing requirement.
The published bond terms establish that the securities are issued under Germany’s Electronic Securities Act, known as the eWpG. The digital securities register is maintained by Cashlink Technologies GmbH in Frankfurt am Main, while Tangany GmbH is appointed as custodian.
The Ratekau investment listing advertised participation from €50, with fixed interest of 5.5% annually and a potential additional performance-related payment of 0.50% per annum, subject to the applicable conditions. The term runs from 1 September 2026 to 31 August 2029, with the platform now showing the financing phase as completed.
The bonds constitute direct, unconditional and unsecured obligations of the issuer, ranking equally with its other existing and future unsecured liabilities. Investors therefore stand alongside other unsecured creditors rather than holding a specific security interest over the solar installation. The investment remains exposed to the issuer’s financial position and the commercial performance of the project.
The marketplace describes repayment as being expected principally from a later sale of the photovoltaic installation or refinancing, alongside potential partial repayments during the term. The issuer will need sufficient funds to meet its obligations when they fall due, regardless of whether electricity revenues perform as forecast.
The listing reports that its fundraising target has been reached, but the publicly displayed completion status does not independently verify the final amount of subscribed and settled capital across all three tranches. The financial performance of the project and its eventual ability to refinance or dispose of the asset will determine whether the underlying investment assumptions are fulfilled.
A comparable initiative emerged in November 2025 when Spanish renewable-energy company Turbo Energy announced a collaboration with Taurus and the Stellar Development Foundation to explore tokenised debt financing for hybrid solar and battery installations.
The proposal focuses on battery-integrated power purchase agreements, beginning with a deliberately small proof of concept at a supermarket in Spain. The intended approach involves financing on-site solar and storage equipment through contractual electricity revenues, with the possibility of extending the structure across additional commercial and industrial installations.
The Turbo Energy announcement filed with the US Securities and Exchange Commission describes an exploratory project intended to validate operational and financial outcomes before wider deployment. It does not establish that a substantial programme of tokenised energy financing has already been completed, although the proposal demonstrates how revenue-producing installations could be incorporated into digital investment structures.
The Economics of Smaller Projects
Large infrastructure developments already have access to established sources of capital. A major motorway concession or electricity transmission network may attract commercial banks, pension funds, infrastructure investment managers and development finance institutions capable of committing substantial amounts of money.
Smaller projects frequently operate in a different financing environment. A district heating network, community energy installation or portfolio of electric vehicle charging stations may have credible revenues and an established customer base, yet still struggle to assemble an economical financing package.
Consider a hypothetical €8 million district heating network serving residential and commercial customers. The developer might obtain conventional bank lending for part of the investment but need additional capital to complete the financing.
A tokenised bond could divide that requirement into smaller securities offered to eligible investors, while digital recordkeeping and automated payments might simplify ongoing administration. Such arrangements could become more attractive where the same financing platform was used across multiple projects, spreading establishment costs over a larger number of transactions.
Distributed solar installations, battery storage facilities, charging networks and small utility systems can share standardised contracts, performance reporting and maintenance arrangements. Financing these assets individually or through portfolios could create sufficient scale to justify specialised securities infrastructure, provided that the benefits exceed the expense of creating and operating the system.
Tokenised securities still require investor identification, compliance checks, financial disclosure, custody arrangements and secure technology. They may also involve specialist legal advice, audited information and ongoing reporting, while smaller investors can introduce additional requirements concerning suitability and marketing.
The OECD’s January 2025 assessment of asset tokenisation identified limited evidence of savings at scale, infrastructure complexity, insufficient standardisation and an underdeveloped market ecosystem among the obstacles to wider adoption.
Dividing an investment into smaller denominations does not necessarily produce additional demand. Institutional investors still evaluate credit quality, commercial returns and the ability to exit an investment, while retail investors require understandable information about the issuer, the underlying project and the circumstances in which they could lose money.
Repeatable financing structures may eventually make digital securities economical for portfolios of smaller assets. For an isolated construction project, the costs of establishing a compliant platform could exceed any savings in administration.
Secondary Markets and Liquidity
Tokenisation is frequently associated with the possibility of making traditionally illiquid infrastructure investments easier to trade. An investor holding an interest in a privately financed motorway or renewable-energy portfolio may ordinarily face restrictions on transferring that investment. Transactions can require extensive documentation, approval from other stakeholders and negotiations with potential buyers.
Representing the interest through digital securities could simplify recordkeeping and the technical transfer process, particularly where investors participate through a regulated trading platform. The existence of a trading mechanism, however, does not establish that anyone is willing to purchase the security at an acceptable price.
Infrastructure investments are often illiquid for commercial reasons. Their value depends on long-term revenue forecasts, asset condition, operating obligations and financing agreements, while reliable valuations require access to information that may not be publicly available.
A toll road illustrates the difficulty. Its income can fluctuate with traffic volumes, economic activity, competing routes and government policy. Maintenance expenditure can be substantial, while concession agreements may restrict ownership changes or require approval from the public authority.
The ECB’s April 2026 research found that tokenised bonds in its matched liquidity analysis exhibited bid-ask spreads averaging 0.05 percentage points lower than those of comparable conventional securities, an improvement of approximately 27%. Lower bid-ask spreads generally indicate that buying and selling can take place with less transaction friction.
The findings reversed for tokenised bonds accessible to retail investors. Those securities exhibited wider spreads, although the authors cautioned that the result was driven by a very small number of retail-accessible tokenised bonds with unusually high spreads.
The sample is too small to establish a general relationship between retail access and poor liquidity, and it should not be treated as evidence about the trading performance of any individual infrastructure bond. It nevertheless challenges the assumption that allowing smaller investors to participate automatically produces a more active secondary market.
The European Securities and Markets Authority’s 2026 risk monitoring warned that tokenisation could make illiquid assets appear liquid, potentially obscuring the practical difficulty of selling an investment.
A platform might technically support continuous trading, but securities held by a small group of specialised investors may generate little activity. In the absence of willing buyers, faster settlement offers limited assistance, while the underlying investment remains exposed to the commercial performance of its associated infrastructure.
Construction Risk, Contracts and Regulation
Traditional project finance is complicated because infrastructure projects contain risks that must be identified, priced and allocated. A lender financing a bridge needs to establish who carries the cost if foundation conditions differ from the original geotechnical investigation, construction is delayed or the contractor becomes insolvent. For a renewable-energy development, equivalent questions concern equipment performance, grid connection, electricity offtake and operational availability.
These considerations produce contractual arrangements involving sponsors, lenders, contractors, insurers, technical advisers and public authorities. Financial models determine how project revenue will be allocated between operating expenditure, debt service, reserves and shareholder distributions, with protections designed to respond when the project encounters difficulties.
Tokenisation could simplify some of the administration surrounding these arrangements, particularly where payments or ownership records can be updated automatically. Smart contracts, which are software instructions designed to execute transactions when specified conditions are satisfied, could potentially automate payments linked to construction milestones.
A payment might be programmed for release following confirmation that a particular stage of work has been completed. An independent engineer or certifier would still be responsible for verifying the physical work, while the financial system would need to recognise contractual conditions, lender restrictions and unresolved disputes. Incorrect information could otherwise cause an automated payment to be processed without the necessary safeguards.
The same considerations apply to debt-service reserves, distribution restrictions and default provisions. These mechanisms protect lenders and investors when a project encounters financial difficulties, and any automated payment structure would need to operate within the agreed contractual framework.
In the European Union, digital tokens qualifying as financial instruments remain subject to securities legislation. The Markets in Crypto-Assets Regulation, or MiCA, expressly excludes crypto-assets that qualify as financial instruments, which remain under the applicable securities framework.
The EU Distributed Ledger Technology Pilot Regime, which began applying in March 2023, provides a framework for authorised market infrastructures to trade and settle eligible financial instruments using distributed ledger technology. It permits experimentation with new arrangements while maintaining requirements concerning investor protection, transparency and financial stability.
Germany’s Electronic Securities Act provides another route for regulated digital issuance. Under the eWpG, securities such as the Ratekau bonds can be issued through registration in a legally recognised crypto-securities register, without conventional paper certificates. The register provides the electronic securities record, with tokens created in connection with the registered interests.
The Ratekau documentation identifies Cashlink Technologies GmbH as register keeper and Tangany GmbH as custodian, while allowing the issuer to replace either provider without bondholder consent. Although such arrangements can provide operational flexibility, they also demonstrate the importance of understanding the rights granted to investors under the securities documentation.
Infrastructure investments may face restrictions extending beyond financial regulation. Concession agreements, public procurement rules, land rights, planning obligations and contractual consent requirements can affect how interests are transferred or controlled, regardless of the technology used to record ownership.
Digital securities may simplify international distribution, but an investment cannot automatically be offered in every jurisdiction. The issuer, platform and intermediaries must still comply with the rules governing the security and its intended investors, which helps explain the continuing participation of established banks, securities firms and legal advisers in major tokenisation programmes.
Operational Assets and Portfolios
Completed infrastructure may provide a more suitable environment for tokenised investment than projects still facing substantial construction uncertainty. A working solar park, district heating network or established toll road has a performance history that investors can examine. Construction risk has largely fallen away, while operating expenditure, maintenance requirements and revenues can be assessed against actual results.
Refinancing such an asset through tokenised securities could therefore be less complicated than raising capital for its initial construction. The investment would still face commercial and financial risks, but fewer assumptions would depend on completing a programme of physical work.
There may also be opportunities in aggregating smaller assets into investment portfolios. A developer operating charging infrastructure across several cities could potentially combine multiple installations through a common financing structure, supported by standardised operating agreements and consistent performance reporting.
Similar arrangements could be explored for distributed solar generation, battery storage, water treatment facilities and other assets with identifiable contractual revenues. Where financing structures can be repeated, the cost of creating and maintaining digital securities infrastructure may be spread across many transactions.
Existing financial products already serve some of these purposes. Infrastructure debt funds, private placements, securitisations and regulated crowdfunding platforms can assemble capital or distribute investment exposure without using blockchain technology. Tokenised alternatives must therefore demonstrate advantages through completed transactions rather than relying on the technical capabilities of distributed ledgers.
Hong Kong’s digital green bond programme demonstrates that regulated issuance can operate at substantial scale and attract institutional investors. The ECB’s research suggests favourable borrowing costs and liquidity in some circumstances, but has yet to establish lower operational costs. Smaller renewable-energy initiatives bring the technology closer to individual physical assets, although their financial performance and long-term investment outcomes remain to be demonstrated.
A successful financing model would need to show lower total transaction expenses, improved access to investors, useful secondary-market liquidity or an ability to fund projects that conventional arrangements struggle to support. Those advantages would have to survive comparison with existing financial structures and remain effective throughout the investment’s life.
Tokenisation cannot improve poor ground conditions, repair an unreliable power purchase agreement or compensate for an unrealistic traffic forecast. It may nevertheless help sound infrastructure projects reach investors more efficiently, particularly where financing arrangements can be standardised and repeated.
The technology has progressed far enough to establish a role in regulated financial markets, while its case as an alternative to conventional infrastructure project finance is still being tested through relatively small projects and a limited record of completed transactions. The eventual measure of success will be less concerned with how investment is recorded than with whether more viable infrastructure can be financed at an acceptable cost.
Key Industry Questions
- What is tokenised infrastructure investment? It is a financing arrangement in which debt, equity or other financial claims associated with infrastructure assets are represented by digital tokens, usually recorded on distributed ledger technology.
- Does purchasing a token provide ownership of physical infrastructure? Not necessarily. A token might represent a bond, an interest in an investment company or a contractual right to payments. Ownership depends on the legal documentation governing the investment rather than the technology used to record it.
- Can infrastructure developers raise money through tokenised bonds? Yes. Regulated tokenised bond structures are already in use, while renewable-energy projects are applying them to physical assets. The issuer must still satisfy relevant financial, legal and regulatory requirements.
- Are tokenised bonds cheaper than conventional financing? Research published by the ECB in April 2026 found lower average borrowing spreads in a matched sample of tokenised bonds. However, it did not establish lower underwriting fees, and the overall financing benefit remains uncertain.
- Which infrastructure projects are most suitable for tokenisation? Operational assets with predictable contractual revenues and repeatable financing structures may provide favourable conditions. Distributed renewable energy, charging infrastructure and smaller utility networks are potential applications.
- Can tokenisation improve investment liquidity? It may simplify securities transfers and settlement, but actual liquidity depends on market demand, reliable valuations and legally transferable rights. Research suggests that improvements are not uniform across different types of tokenised securities.
- Does tokenisation remove the need for banks and technical advisers? No. Project appraisal, legal structuring, financial compliance, independent engineering and investor protection remain necessary. Digital systems may automate parts of the administration without eliminating these responsibilities.
- Can tokenised financing be used for public-private partnerships? Potentially. Tokenised debt or equity could form part of a PPP financing structure, provided the arrangement complies with concession agreements, lender requirements, securities regulation and applicable public-sector restrictions.
- Are tokenised infrastructure investments regulated in Europe? Where tokens qualify as financial instruments, applicable securities legislation governs their issuance and trading. The EU DLT Pilot Regime provides a specific framework for eligible market infrastructures, while national laws such as Germany’s Electronic Securities Act support particular forms of digital issuance.
- What would prove the commercial value of infrastructure tokenisation? Completed projects demonstrating lower total financing costs, additional investor participation, reliable secondary-market liquidity or access to capital unavailable through comparable conventional arrangements would provide stronger evidence of practical value.
Strategic Takeaways
- Operational assets may offer the clearest early opportunities. Established revenues and performance records allow investors to evaluate infrastructure without the full uncertainty of construction delivery.
- Portfolio financing could justify the technology. Standardised structures across multiple smaller assets may spread legal, administrative and technology costs more effectively than isolated transactions.
- Lower borrowing spreads do not establish lower financing costs. The ECB’s findings show that favourable bond pricing can coexist without lower underwriting expenses.
- Retail accessibility does not guarantee liquidity. Smaller investment denominations may widen participation, but functioning secondary markets still require buyers, reliable valuations and enforceable rights.
- Additional capital is the stronger commercial test. Tokenisation becomes more compelling when it helps viable infrastructure projects secure funding that existing structures cannot provide efficiently.