From Lobito to Lagos: 10 Infrastructure Projects to Watch Across Africa
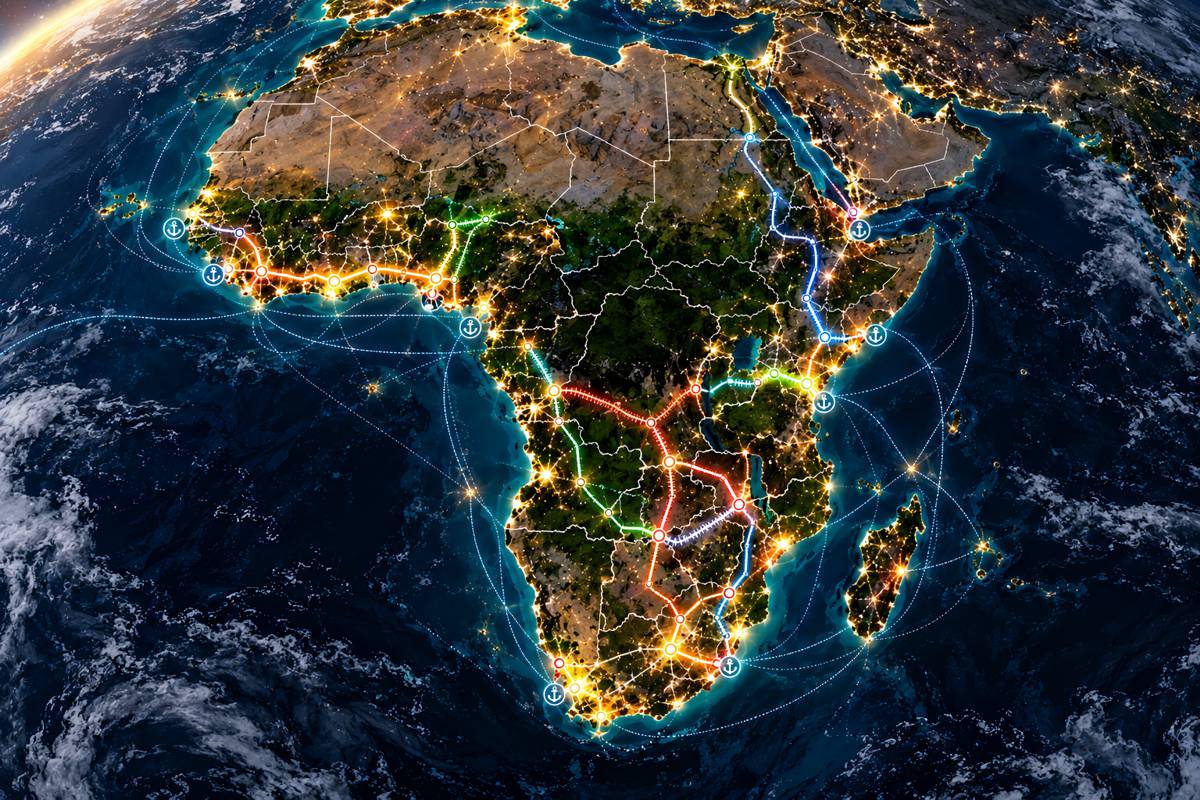
Across Africa, some of the continent’s most consequential infrastructure projects are doing more than reducing journey times. They are changing where roads and railways lead.
In Southern and Central Africa, new investment is creating alternative routes from the mineral-rich Copperbelt towards ports on the Atlantic and Indian Oceans. Guinea has built a railway across the country to unlock the Simandou iron ore deposits and connect them with new port infrastructure. East Africa is extending standard-gauge railways inland from Kenya and Tanzania, while West African governments are preparing a 1,028 km highway intended to connect five national economies between Abidjan and Lagos.
The projects vary enormously in purpose and maturity. Some are entering operation, others are deep into construction, while several are still assembling the finance and contracts required to turn regional ambitions into physical infrastructure.
Briefing
- The existing Lobito railway has reached financial close on a $753 million rehabilitation and operating programme, while a separate 830 km greenfield railway is being developed to connect the corridor directly with Zambia.
- Guinea’s Simandou transport system includes more than 600 km of railway, 206 bridges, four tunnels and new Atlantic port infrastructure capable of supporting exports on an exceptional scale.
- Kenya and Uganda are extending their standard-gauge railway systems towards each other, creating the foundations for a continuous modern railway between Mombasa and Kampala.
- The proposed Abidjan-Lagos Corridor Highway would extend approximately 1,028 km through five West African countries at an estimated cost of around $14.7 billion.
- China-backed rehabilitation of TAZARA and internationally backed development of the Lobito Corridor are creating alternative east-west transport routes for the Central African Copperbelt.
1. Lobito Corridor, Angola, DRC and Zambia
Few infrastructure programmes demonstrate Africa’s emerging corridor economy as clearly as Lobito.
The existing railway runs approximately 1,300 km from the Atlantic port of Lobito across Angola to the border with the Democratic Republic of Congo, providing the western spine of a route towards the copper and cobalt producing regions of Central Africa.
That railway has now reached an important commercial milestone. In July 2026, a $753 million financing package reached financial close for rehabilitation, upgrading and long-term operation of the Angolan corridor. The package comprises $553 million from the US International Development Finance Corporation and $200 million from the Development Bank of Southern Africa.
The borrower and concessionaire is Lobito Atlantic Railway, a joint venture involving Mota-Engil and Trafigura.
A separate and considerably more ambitious project would carry the corridor into Zambia. The Zambia Lobito Railway is planned as approximately 830 km of new greenfield railway between Chingola in Zambia and Luacano in Angola, where it would connect with the existing Benguela railway.
Africa Finance Corporation is leading development of the new line under concession agreements with Angola and Zambia. Environmental and resettlement work has progressed during 2026, while procurement has moved towards selection of EPC contractors for civil works in both countries and a separate package covering signalling, railway systems and rolling stock.
The timetable shows how far this part of Lobito still has to travel. Project financing is being assembled, with financial close currently targeted for the fourth quarter of 2027 before full construction can proceed.
The distinction between the two investments is important. One is a financed rehabilitation and operating programme for an existing railway. The other is an 830 km greenfield railway still moving through procurement and financing.
If both succeed, they would create something much larger: a direct modern rail route from Zambia’s Copperbelt towards the Atlantic, reducing dependence on longer routes through Southern and Eastern Africa.
2. Simandou Railway and Port, Guinea
In Guinea, the development of the Simandou iron ore deposits has effectively required the construction of a new national transport system.
The deposits lie more than 600 km inland in the mountainous south-east of the country. Exporting ore at scale has therefore required a new railway across Guinea and major port infrastructure at Morebaya on the Atlantic coast.
The numbers reveal the scale of the civil engineering. The approximately 600 km dual-track main railway incorporates 12 stations, 206 bridges and four tunnels as it crosses six of Guinea’s eight administrative regions. Winning Consortium Simandou has constructed the main line and its connection with its mining blocks, while SimFer has built a separate 78 km spur from Blocks 3 and 4.
That spur alone includes a 908 metre tunnel, five major bridges, water crossings and wildlife crossings.
At the coast, WCS is developing a four-berth barge terminal capable of handling 60 million tonnes annually. SimFer is building a separate three-berth transhipment vessel terminal with another 60 million tonnes of annual capacity, alongside rail unloading, conveyors, stockpiles, power and fuel infrastructure.
The investment is correspondingly large. Rio Tinto expects its own share of the SimFer development to reach approximately $6.2 billion within an estimated $11.6 billion required to complete SimFer’s mine, rail spur and share of the common railway and port infrastructure.
By the first half of 2026, the project was already moving beyond construction. The shared rail network had been fully commissioned during the first quarter, 2.2 million tonnes of ore had been shipped during the first half of the year, and SimFer’s port infrastructure had reached approximately 85% completion.
The transport system will ultimately be owned and operated through La Compagnie du TransGuinéen, in which SimFer and WCS each hold 42.5% and the Guinean state 15%.
That structure matters because the railway is intended as multi-user infrastructure rather than a private siding serving a single mine. Simandou is therefore becoming a test of whether resource-led investment can leave Guinea with transport infrastructure useful beyond the commodity that paid for it.
3. Tanzania Standard Gauge Railway, Tanzania
Tanzania’s Standard Gauge Railway is steadily pushing inland from the Indian Ocean towards the heart of East Africa.
The system begins at Dar es Salaam and runs west through Morogoro, Dodoma and Makutupora, with construction continuing towards Tabora, Isaka and ultimately Mwanza. Longer-term connections towards Kigoma, Burundi and the Democratic Republic of Congo would turn the railway into an increasingly important component of the Central Corridor.
The western construction packages demonstrate the scale still under way.
The Makutupora-Tabora section includes approximately 294 km of main line and 74 km of passing tracks. Its construction contract is valued at approximately $1.908 billion and includes eight passenger and freight stations as well as railway control infrastructure.
From Tabora, another package continues towards Isaka. The contract with Turkish contractor Yapı Merkezi is worth approximately $900 million and covers around 119 km of main line plus sidings, three stations, a maintenance workshop, depot, signalling, telecommunications and electrification.
Yapı Merkezi has consequently become one of the defining contractors on Tanzania’s SGR, having delivered or worked across several successive sections of the route.
The railway’s economic importance extends beyond Tanzania. Dar es Salaam serves as a maritime gateway for landlocked economies including Rwanda, Burundi, Zambia and the Democratic Republic of Congo. Every additional section completed inland increases the area from which freight can potentially reach the Indian Ocean by modern railway rather than long-distance road transport.
The engineering is substantial, but the larger test will come at the interfaces: ports, border crossings, connecting railways and freight terminals will determine whether a national railway becomes a regional corridor.
4. Malaba-Kampala Standard Gauge Railway, Uganda
Uganda is preparing the next major link in East Africa’s emerging standard-gauge railway network.
The Malaba-Kampala railway will extend approximately 272 km from the Kenyan border to the Ugandan capital. Turkish contractor Yapı Merkezi secured the EPC/turnkey contract in October 2024, replacing the earlier Chinese contracting arrangement after years of difficulty securing finance.
The project is currently estimated at around €2.7 billion. Uganda appointed Citibank in April 2026 to help mobilise financing, while discussions have also taken place with the World Bank.
A significant part of that financing picture changed in June when the Islamic Development Bank approved €650.75 million, the largest financing approval it has made for a single Ugandan project. The funding is earmarked for some of the route’s most substantial engineering works.
These include a 553 metre bridge across the Nile, a 2.12 km tunnel between Mbuya and Kampala, six stations at Tororo, Iganga, Jinja, Lugazi, Kampala East and Kampala City, and workshops at Kampala East, Jinja and Tororo.
Preparatory works have begun with Ugandan government funding, but full-scale construction remains dependent on completing the wider financing package. The government has been working towards financial close during 2026.
That makes Malaba-Kampala both an engineering project and a financing story.
Its value also depends on what happens on the other side of the border. For years, Uganda’s railway ambitions were constrained by uncertainty over whether Kenya would extend its own standard-gauge system west from Naivasha.
That situation has now changed.
5. Naivasha-Kisumu-Malaba Standard Gauge Railway, Kenya
In July 2026, actual construction began on the next major extension of Kenya’s Standard Gauge Railway.
Phase 2B will run approximately 264 km from Naivasha to Kisumu, with an additional 8.69 km branch serving the proposed new Kisumu Port. Phase 2C would continue another 107 km from Kisumu to Malaba on the Ugandan border.
The wider Naivasha-Malaba programme has been associated with investment of around KSh700 billion, with Chinese contractors China Communications Construction Company and China Road and Bridge Corporation involved in delivery.
Construction on the Naivasha-Kisumu section formally moved onto the ground in July, with work beginning from both ends of the route.
The geography is significant. The railway crosses the Rift Valley and continues through Narok, Bomet, Kericho, Nyamira and Kisumu, requiring substantial earthworks and structures before reaching Lake Victoria. From Kisumu, the final section would extend through western Kenya towards Malaba.
Its importance becomes clearer when viewed beside Uganda’s project. Kenya is building west while Uganda is preparing to build east.
Once the two systems meet at Malaba, a modern standard-gauge route could run from Mombasa through Nairobi and the Rift Valley to Kampala. Uganda’s longer-term ambitions would carry it farther towards the Democratic Republic of Congo.
That is the corridor principle becoming physical: projects procured and financed separately by neighbouring governments only realise their full value when the rails eventually meet.
6. Abidjan-Lagos Corridor Highway, West Africa
The proposed Abidjan-Lagos Corridor Highway is attempting something even more ambitious: treating a road through five countries as a single piece of infrastructure.
The six-lane motorway would extend approximately 1,028 km through Côte d’Ivoire, Ghana, Togo, Benin and Nigeria, connecting Abidjan, Accra, Lomé, Cotonou and Lagos.
Its estimated cost is around $14.7 billion, with a mixed public-private financing structure under development.
The project has advanced beyond its initial technical and economic studies but is not yet a 1,028 km construction site. ECOWAS, the African Development Bank and participating governments are working through the investment stage, including financing, project packaging, land acquisition and the structures required for future tendering.
The African Development Bank is acting as mandatory lead arranger as the programme attempts to mobilise concessionary and private-sector capital.
The institutional design is almost as interesting as the road itself. The five governments have agreed that the corridor should be designed, constructed and operated as one road, supported by a supranational management authority.
That matters because the existing coastal corridor already connects one of Africa’s densest concentrations of population and economic activity. The infrastructure problem is not simply absence of demand. It is the friction involved in moving people and freight between major cities and across national borders.
The physical programme will eventually require enormous quantities of pavement, bridges, interchanges, drainage, border infrastructure and urban road works. But a truck gaining hours on a motorway and losing them again at a border has gained little.
Abidjan-Lagos will therefore succeed only if construction and regional trade reform progress together.
7. Lagos-Calabar Coastal Highway, Nigeria
Nigeria is already constructing another enormous road along its southern coastline.
The Lagos-Calabar Coastal Highway is planned to extend approximately 750 km from Lagos towards Cross River State, eventually passing through nine states.
Hitech Construction is delivering the initial works under an EPC+F structure. A $747 million syndicated loan has been arranged for Phase 1 Section 1, with lenders including First Abu Dhabi Bank, Afreximbank, the Abu Dhabi Exports Office, the ECOWAS Bank for Investment and Development and commercial banks.
The first 103 km lies within Lagos State and is being delivered in phases. The initial 47.4 km runs from the Ahmadu Bello Way area towards Eleko, followed by another 55.6 km towards the Lagos-Ogun boundary.
The engineering choice is notable. The highway uses continuously reinforced concrete pavement, accompanied by major drainage and culvert works, median barriers, lighting and extensive relocation of electricity, gas and water infrastructure.
Thirty kilometres of the first section had already been commissioned by May 2025, and Phase 1 Section 1 was reported more than 70% complete when the international financing package was announced.
The coastal environment will remain a recurring engineering challenge as construction moves east. High groundwater, drainage, settlement, erosion and existing development all complicate the construction of a long new road corridor close to the shoreline.
Financing for later phases is still being structured, meaning the 750 km vision should not be confused with the portion already contracted and funded. The scale is continental; delivery remains sectional.
8. Lesotho Highlands Water Project Phase II, Lesotho and South Africa
Not every important African corridor carries vehicles or freight.
Phase II of the Lesotho Highlands Water Project is expanding the system that transfers water from the mountains of Lesotho towards South Africa while supporting hydropower generation within Lesotho.
At its centre is the Polihali Dam, a concrete-faced rockfill structure that will stand 166 metres high with a crest 921 metres long. Its embankment will contain more than 14 million cubic metres of locally quarried rock and create a reservoir capable of storing approximately 2.325 billion cubic metres of water.
The second major structure is the Polihali Transfer Tunnel, approximately 38.5 km long with a nominal five-metre bore, carrying water by gravity towards the existing Katse Reservoir.
Construction is well advanced. LHDA reported in March 2026 that the dam was 44% complete and the transfer tunnel 51% complete, while advance infrastructure had reached 97%. The Senqu bridge was effectively complete and the Khubelu and Mabunyaneng bridge works had reached 70%.
Tunnel boring has also entered a new stage. The first TBM began from the Katse side, while a second machine was launched from Polihali in April 2026, allowing excavation to proceed from both ends of the 38.5 km alignment.
The dam contract, worth approximately M7.68 billion when awarded, is being delivered by SUN Joint Venture, bringing together Sinohydro Bureau 8, Sinohydro Bureau 14, Unik Civil Engineering and Lesotho’s Nthane Brothers. The transfer tunnel is being delivered by KKM Joint Venture, involving Yellow River, Sinohydro Bureau 3 and Unik Civil Engineering among its principal partners.
When Phase II enters operation, annual water transfer capacity from Lesotho towards South Africa is intended to rise from around 780 million cubic metres to approximately 1.27 billion cubic metres.
For Gauteng, home to Johannesburg, Pretoria and much of South Africa’s industrial economy, that makes a dam and tunnel high in the mountains of Lesotho part of the infrastructure supporting everyday economic activity hundreds of kilometres away.
9. TAZARA Revitalisation, Tanzania and Zambia
One of Africa’s most historically significant railways is beginning another transformation.
The Tanzania-Zambia Railway runs approximately 1,860 km between Dar es Salaam and New Kapiri Mposhi in Zambia. Built with Chinese support during the 1970s, it gave landlocked Zambia an alternative route to the sea at a time when regional politics made southern export corridors increasingly difficult.
In September 2025, TAZARA signed a public-private partnership concession with China Civil Engineering Construction Corporation to rehabilitate, modernise and operate the freight railway.
The investment exceeds $1.4 billion.
Approximately $1 billion is intended for rehabilitation of track and railway infrastructure, while another $400 million is allocated to 32 new locomotives and 762 wagons. The 30-year concession envisages roughly three years of construction and rehabilitation followed by 27 years of operating management.
By 2026, the programme was moving from agreement towards visible implementation.
Its renewed importance is closely connected with the Copperbelt. Zambia and the Democratic Republic of Congo contain some of the world’s most important copper and cobalt resources, while demand for those commodities is being reinforced by investment in electricity networks, renewable energy and electrified transport.
To the west, the Lobito Corridor is being strengthened towards Angola and the Atlantic. To the east, TAZARA points towards Dar es Salaam and the Indian Ocean.
Those programmes are often viewed through geopolitical competition between China and Western governments. For the countries along the routes, another interpretation may be more useful: competition is creating alternatives.
A landlocked mining region with more than one viable route to global markets has greater logistical resilience, and potentially greater negotiating power, than one dependent on a single corridor.
10. Durban Container Terminal Pier 2, South Africa
Africa’s corridor economy ultimately depends on what happens when roads and railways reach the coast.
Durban Container Terminal Pier 2 is therefore a very different infrastructure project from the new railways and highways elsewhere on this list. The asset already exists, but its performance is sufficiently important to South African and regional trade that modernising it has become a strategic infrastructure programme.
In December 2025, Transnet and International Container Terminal Services signed a 25-year partnership covering operation, upgrade and development of Pier 2. The arrangement took effect in January 2026 through a new special-purpose vehicle in which Transnet retains the majority interest while ICTSI operates the terminal.
The targets are substantial.
Capacity is intended to rise from around 2 million to 2.8 million twenty-foot equivalent units annually. Gross crane moves are targeted to increase from 18 to 28 per hour, while ship working performance is expected to double from around 60 to 120 container moves per hour.
Achieving that requires investment in equipment, technology and terminal systems alongside changes in operating practice.
The significance extends far beyond Durban. South Africa’s ports and freight railways serve mining, manufacturing and agricultural supply chains across the country and into neighbouring economies. When terminal productivity deteriorates, the effects travel backwards through railway sidings, warehouses, factories and mines.
Durban illustrates a different African infrastructure challenge. In some places the priority is building a missing railway. In others it is extracting substantially more capacity and reliability from infrastructure that already exists.
Adding quay capacity or new cranes will not solve the wider logistics problem if trains cannot reach the terminal reliably or containers remain trapped elsewhere in the system. The commercial partnership at Pier 2 will therefore be judged not simply by construction and equipment installation, but by whether physical investment translates into dependable freight movement.
Corridors Change the Map
Africa’s infrastructure challenge is often described as a shortage of roads, railways, ports, electricity and water systems. The projects now moving forward suggest something more specific: investment is increasingly concentrating on the connections between economic regions.
The Copperbelt illustrates the change particularly clearly. Lobito is creating a stronger route west towards the Atlantic while TAZARA is being rebuilt towards the Indian Ocean. Farther east, Kenya and Uganda are extending railway infrastructure towards each other, while Tanzania’s SGR is pushing inland from Dar es Salaam.
These projects are also drawing on a wider range of capital and delivery models. African governments and development banks sit alongside Chinese institutions and contractors, Western development finance, Gulf lenders, commercial banks and private operators. Competition between financiers and routes can itself become an infrastructure advantage when it gives countries more than one viable connection to markets.
The engineering remains formidable, but the most difficult interfaces are often beyond the construction site. Railways crossing borders need compatible operations. Highways need functioning customs systems. Ports require reliable inland connections. Water infrastructure shared between countries requires decades of coordinated management.
Across Africa, infrastructure is no longer simply filling gaps on individual national maps. The more consequential projects are beginning to redraw the routes between them.
Key Industry Questions
- What is being built as part of the Lobito Corridor? The existing 1,300 km railway across Angola is undergoing a $753 million rehabilitation and operating programme, while a separate approximately 830 km greenfield railway is being developed between Luacano in Angola and Chingola in Zambia.
- Is the Zambia Lobito Railway already under construction? Not yet at full scale. Environmental and resettlement work has advanced and EPC procurement is under way, while project financing is being assembled. Financial close is currently targeted for the fourth quarter of 2027.
- How large is the Simandou railway? The main trans-Guinean railway extends approximately 600 km and includes 206 bridges, four tunnels and 12 stations. Additional mine spurs connect the main line with the Simandou deposits.
- Who is building Tanzania’s western SGR sections? Turkish contractor Yapı Merkezi is delivering major packages including Makutupora-Tabora and the approximately $900 million Tabora-Isaka contract.
- How much will Uganda’s Malaba-Kampala SGR cost? The 272 km railway is currently estimated at around €2.7 billion. The Islamic Development Bank approved €650.75 million in June 2026, while Uganda is assembling the remaining financing.
- How much could the Abidjan-Lagos Corridor Highway cost? ECOWAS has put the current estimate at approximately $14.7 billion for the 1,028 km six-lane corridor through Côte d’Ivoire, Ghana, Togo, Benin and Nigeria.
- How advanced is Lesotho Highlands Water Project Phase II? In March 2026, the Polihali Dam was reported 44% complete and the transfer tunnel 51% complete, with tunnelling now progressing from both ends.
- How much is being invested in TAZARA? CCECC’s 30-year concession provides for investment exceeding $1.4 billion, including approximately $1 billion for railway infrastructure and $400 million for new locomotives and wagons.
- Why are Lobito and TAZARA strategically important? They provide alternative westward and eastward routes between the mineral-rich Central African Copperbelt and international ports on the Atlantic and Indian Oceans.
- What is changing at Durban Container Terminal Pier 2? Transnet and ICTSI have entered a 25-year partnership to upgrade and operate the terminal, targeting an increase in capacity from around 2 million to 2.8 million TEU annually alongside substantially improved crane and vessel productivity.
Strategic Takeaways
- Africa’s most consequential infrastructure programmes are increasingly being developed as economic corridors rather than isolated national assets.
- Investment in Lobito and TAZARA is creating alternative routes between Central Africa’s mineral regions and ports on opposite sides of the continent.
- Kenya and Uganda are now constructing or preparing adjoining railway sections that could create a continuous modern rail corridor between Mombasa and Kampala.
- Resource development remains a powerful catalyst for infrastructure, but Simandou demonstrates how mining investment can also create railway and port assets with wider national potential.
- African governments are drawing finance and expertise from development banks, China, Western institutions, Gulf lenders, commercial banks and private operators rather than relying on a single infrastructure model.
- Cross-border roads and railways only deliver their full value when customs, ports, connecting networks and operating systems work as effectively as the physical infrastructure.