The Bitumen Supply Crisis Reshaping Global Road Construction
How Geopolitical Conflict, Refinery Disruption and Changing Trade Routes Are Transforming International Bitumen Supply
Germany’s bitumen production fell by approximately 16 percent during the first half of 2026 as shortages of suitable heavy crude affected refinery output. In France, production failures pushed delivered prices to their highest levels in four years, while Singapore’s bitumen market experienced its own supply constraints as Asian refiners struggled to secure appropriate feedstocks. Across three major markets, the difficulties exposed vulnerabilities that crude oil prices alone could not explain.
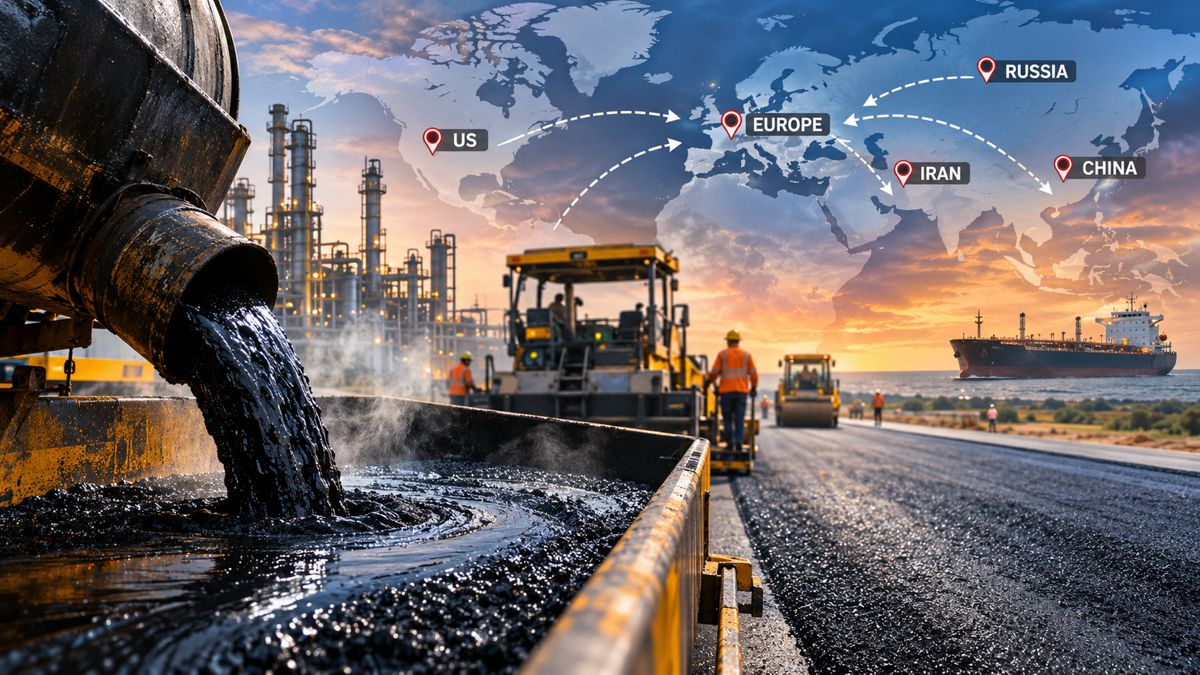
The disruption has been building since Russia’s invasion of Ukraine in 2022, but the conflict involving Iran during 2026 has brought additional pressure to international petroleum markets. Restrictions affecting shipping through the Strait of Hormuz have altered refinery operations across Europe and Asia, while sanctions, changing trading relationships and increasingly unpredictable freight economics have complicated international sourcing.
For highway contractors, the consequences extend beyond material costs. Major infrastructure projects can take years to complete, yet the availability and price of bitumen may depend on refinery production decisions, shipping arrangements and international events unfolding over considerably shorter periods. Securing sufficient material for an entire construction programme is becoming a more complicated commercial undertaking.
Briefing
- German production: Bitumen output fell approximately 16 percent to 1.17 million tonnes during the first half of 2026, partly because of shortages of suitable Middle Eastern heavy crude.
- European shortages: French delivered bitumen prices reached approximately €617.50 per tonne in June, their highest level since 2022, as refinery maintenance and technical failures restricted supply.
- Asian markets: Singapore FOB penetration-grade 60/70 bitumen reached US$660 per tonne in September amid feedstock shortages and refinery production constraints.
- Changing trade routes: The EU imported approximately 15,269 tonnes of petroleum bitumen from the United States in 2025, while the UK separately imported nearly 23,000 tonnes.
- Construction exposure: Short-term material availability and changing pricing arrangements are complicating procurement for contractors delivering long-term infrastructure projects.
Russia and the Restructuring of European Supply
Russia’s invasion of Ukraine fundamentally altered Europe’s petroleum trading relationships. The subsequent sanctions regime restricted Russian oil and petroleum product imports, forcing refiners, traders and distributors to reconsider supply arrangements that had supported established commercial relationships for decades.
The Council of the European Union identifies bitumen and asphalt among products covered by import prohibitions, alongside wider restrictions affecting crude oil and refined petroleum products. European buyers have consequently had to examine alternative sources while accounting for sanctions compliance, financing arrangements, insurance and the origin of imported material.
The effects are not confined to the direct loss of Russian bitumen exports. Refiners previously processing Russian crude have had to adjust their feedstock supplies, while restrictions and changing international demand have redirected petroleum shipments towards different markets. Some replacement crude grades behave differently during refining, affecting the quantities and characteristics of the heavy residues used to manufacture paving bitumen.
Russia remains a significant participant in international petroleum trading, although the destinations and commercial arrangements for its production have changed. For European buyers, the challenge involves securing both finished bitumen and the crude oil required by domestic refineries to maintain production.
These pressures intensified during 2026 as the conflict involving Iran disrupted another important source of heavy crude, creating difficulties for refiners already operating within a substantially altered international supply network.
Iran and the Shortage of Suitable Heavy Crude
Iran occupies an important position in the international bitumen trade, supplying penetration-grade material used in highway construction and other industrial applications. Iranian-origin products have traditionally reached overseas customers through bulk shipments, steel drums and alternative packaging arrangements suited to different importing markets.
The conflict involving Iran during 2026 disrupted petroleum movements throughout the wider Gulf region. Restrictions affecting the Strait of Hormuz interfered with crude oil shipments from several producing countries, leaving import-dependent refineries searching for alternative feedstocks while competing for limited supplies of suitable heavy grades.
The European Central Bank’s November 2026 Economic Bulletin reported substantially reduced refinery activity across the Middle East, Russia and Asia. Brent crude oil had exceeded US$110 per barrel at the end of October, close to 60 percent above pre-conflict levels, while refinery margins and production costs remained elevated.
Bitumen production is particularly sensitive to the composition of crude oil entering a refinery. Different crude grades produce different proportions of residual material, and substituting lighter oil for a heavier feedstock can reduce bitumen yields even when overall refinery throughput remains relatively stable. Refinery configurations and product specifications also determine whether the remaining material is suitable for road construction.
Germany provided a clear example during the first half of 2026. According to Argus reporting published in September, national bitumen production declined by approximately 16 percent year on year to 1.17 million tonnes, with the shortage of suitable Middle Eastern heavy crude contributing to reduced output.
Production fell particularly sharply during May and June. German refinery output was more than 30 percent lower year on year in May, reaching 247,000 tonnes, while June production declined by approximately 20 percent to 254,000 tonnes. Some facilities processing lighter replacement crudes produced less bitumen while maintaining output of other petroleum products, including diesel and aviation fuel.
The Karlsruhe refinery was among the operations affected by changing feedstock availability through the Transalpine Pipeline system. The difficulties demonstrated the limitations of replacing one crude oil source with another, particularly when the required product depends on specific characteristics of the original feedstock.
Refiners cannot necessarily compensate for shortages by purchasing any available crude oil. Even where alternative supplies can be obtained, production economics, refinery configurations and product specifications may prevent the manufacture of equivalent quantities of paving-grade bitumen.
European Refinery Disruption and Regional Shortages
Feedstock restrictions were accompanied by refinery maintenance, technical failures and logistical constraints across several European markets during 2026. These difficulties became particularly visible during the summer construction season, when demand for road surfacing materials was relatively strong.
In June delivered bitumen prices in northern and central France had reached approximately €617.50 per tonne, their highest level since 2022. Some spot transactions were being discussed at prices approaching €630 per tonne despite softer conditions in parts of the wider petroleum market.
The increase coincided with maintenance at TotalEnergies’ Donges refinery and operational difficulties affecting the Gonfreville and Port-Jérôme facilities. TotalEnergies declared force majeure on bitumen supplies from Gonfreville at the end of May following a major technical incident, while other production constraints further restricted domestic availability.
French buyers responded by seeking additional supplies from neighbouring markets, including Belgium, the Netherlands, Germany and Spain. Maritime imports helped compensate for reduced domestic production, although securing material elsewhere introduced additional freight, handling and scheduling considerations.
Supply difficulties also affected the Benelux market. During July problems involving refinery production and cargo handling around Antwerp, prompting some buyers to expand their searches to alternative European sources.
Northern Italian material became one of the options considered as regional distributors attempted to maintain deliveries. However, the movement of bitumen between markets depends on specialised storage, heated transportation and suitable loading facilities. Additional cargoes cannot always be introduced quickly, particularly where ports and terminals are already operating close to their practical capacity.
Bitumen must generally be maintained at suitable temperatures during bulk handling and transport, adding operational complexity and cost compared with many other petroleum products. Marine tankers, storage terminals and road vehicles require appropriate equipment, while delays can affect loading schedules and downstream distribution.
Conditions had become more varied by November, with reduced seasonal construction activity easing pressure in some European markets. The summer shortages nevertheless exposed how local refinery failures can quickly create wider regional problems when several countries depend on overlapping sources of supply.
China and the Changing Asian Supply Balance
Asian bitumen markets have faced related difficulties, although the effects differ considerably between countries and refinery systems.
China is both a major consumer of petroleum bitumen and an important participant in international crude oil trading. Its domestic refining operations, infrastructure investment programmes and relationships with overseas petroleum suppliers can influence demand and availability across neighbouring markets.
According to World Bank trade data, China imported approximately 3.93 million tonnes of petroleum bitumen during 2025, placing it among the world’s largest importing markets. Changes in domestic production, infrastructure demand or the availability of imported crude can therefore have consequences for regional trade flows.
The disruption of Iranian crude shipments and restrictions affecting Russian petroleum trading have complicated feedstock purchasing for some Chinese refiners. Independent operators have increasingly had to consider alternative crude sources, including producers in Africa and the Americas, while balancing transportation costs against refinery requirements.
Singapore experienced particularly pronounced bitumen supply constraints during September.
On 15 September, S&P Global Energy reported that FOB Singapore penetration-grade 60/70 bitumen had reached US$660 per tonne on 11 September, its highest assessment in five months. Refiners were struggling to obtain sufficient suitable heavy crude, while production difficulties and specification issues restricted the quantities available for immediate purchase.
Some output remained committed under existing term contracts, reducing the material available to spot-market buyers. Similar feedstock constraints affected parts of South Korea’s refining sector, adding to competition for alternative supply sources.
The interaction between Chinese demand, regional refinery production and changing crude oil shipments has made Asian pricing increasingly dependent on local circumstances. Contractors and importers in Southeast Asia, South Asia and Africa can consequently face different supply conditions even when purchasing similar grades of bitumen.
International crude oil benchmarks remain important, but they provide only part of the information needed to understand the availability and price of finished bitumen in a particular market.
US Exports and the Changing Geography of Supply
The movement of petroleum bitumen from the United States into European markets provides another perspective on the changing international trading system.
The United States is a substantial consumer and importer of bitumen, supported by its extensive highway network and large asphalt paving industry. Nevertheless, its refining sector also produces material for international export, with supply moving between regions according to refinery output, product specifications and commercial conditions.
World Bank World Integrated Trade Solution data shows that the European Union imported approximately 15,269 tonnes of petroleum bitumen from the United States during 2025, with a reported value of US$9.94 million.
The United Kingdom separately imported approximately 22,979 tonnes from the United States during the same year, valued at around US$11.85 million. These figures establish that transatlantic bitumen trade was already taking place before the latest Middle Eastern disruption, although comparable 2026 data would be required to determine whether those flows have subsequently increased.
The economics of international bitumen trading can favour apparently unconventional routes when regional refinery production becomes constrained. A European importer may find competitively priced material in North America even after allowing for transatlantic transportation, particularly where domestic suppliers cannot provide the required volumes within the available delivery window.
Distance is only one component of the calculation. Marine freight, vessel availability, port charges, heated storage, inland distribution and product specifications all influence the final cost. A low FOB quotation can become considerably less attractive once the cargo has reached its destination and undergone the handling required for delivery to an asphalt plant.
The same considerations apply to alternative sourcing from the Middle East, Turkey, Asia and other producing regions. Importers must establish whether the material satisfies the applicable road construction standards, whether sufficient quantities are genuinely available and whether the logistical arrangements can support the proposed delivery programme.
For larger infrastructure projects, the reliability of those arrangements can be as commercially important as the initial price difference between competing suppliers.
The Growing Procurement Problem for Road Contractors
International supply disruption creates a particular difficulty for road construction because the commercial timescales of infrastructure projects are very different from those of petroleum trading.
A highway authority may approve a multi-year investment programme, with contractors committing to prices and construction schedules well before all the required materials have been purchased. Asphalt production then depends on timely deliveries of aggregates, bitumen and other constituents, often during relatively narrow seasonal construction windows.
Where contractors can negotiate long-term supply agreements, they may obtain greater certainty over availability and purchasing arrangements. However, those agreements do not necessarily guarantee fixed prices, and suppliers may introduce index-linked formulas, shorter quotation periods or provisions addressing changes in market conditions.
The extent to which refiners are becoming less willing to guarantee forward quantities remains difficult to establish across the industry. Existing term contracts continued to influence market availability in Singapore during September, demonstrating that longer-term commitments remain an important feature of international supply. They can also restrict opportunities for buyers seeking additional material when production is constrained.
Spot purchasing provides flexibility but exposes contractors to different risks. Material may be available when required, but at prices that differ substantially from those assumed during tender preparation. Alternatively, a contractor willing to accept a higher price may still struggle to obtain the necessary grade, quantity or delivery schedule.
The consequences can be particularly serious for asphalt production. A plant designed to produce mixes using a specified penetration, viscosity or performance-graded binder cannot necessarily substitute another material without checking technical requirements, mix design compatibility and contractual approvals.
Interrupted deliveries can delay paving operations, increase equipment standby costs and disrupt subcontractors whose activities depend on completed road sections. Where project contracts provide limited protection against material escalation or supply interruption, additional costs may fall disproportionately on the contractor.
Smaller businesses are especially exposed when they lack the purchasing volumes, storage capacity or financial resources available to larger organisations. Securing additional stock can protect against temporary shortages, but heated bitumen storage involves capital investment, energy consumption and operating costs that may be difficult to justify for occasional projects.
These pressures are encouraging closer examination of supply agreements, pricing mechanisms and the practical availability of alternative sources. Contractors purchasing imported material must also consider payment security, independent quality inspection, shipping documentation and the reliability of intermediaries operating across several jurisdictions.
A supplier capable of offering a competitive price is not necessarily capable of delivering a substantial volume of specification-compliant bitumen to a remote construction project at the required time.
Building More Resilient Bitumen Supply Chains
The disruptions experienced during 2026 have placed greater emphasis on the resilience of bitumen procurement arrangements. Buyers dependent on a single refinery, terminal or trading route can face significant difficulties when production is interrupted, even where alternative supplies remain available in the wider international market.
Diversifying suppliers offers one possible response, although maintaining several commercial relationships does not automatically guarantee access to additional material. Buyers need to understand where their suppliers obtain bitumen, whether production is supported by reliable feedstocks and which transport arrangements are required to reach the final destination.
Technical verification remains equally important. International procurement can involve different systems of penetration, viscosity and performance grading, alongside national standards and project-specific specifications. Documentation, laboratory testing and independent inspection may be necessary before replacement material can be accepted for construction.
Storage and distribution infrastructure can provide additional flexibility where project scale and market conditions justify the investment. Heated terminals, strategically located depots and reliable road tanker capacity can allow importers to respond to changes in refinery availability, although these facilities introduce their own capital and operating costs.
Contracting arrangements also deserve renewed attention. Price-adjustment provisions, clearly defined delivery commitments and realistic procedures for dealing with material shortages can help allocate commercial risk between project owners, contractors and suppliers. Their effectiveness depends on the terms of individual agreements and the availability of suitable purchasing benchmarks.
The market developments reported during 2026 do not indicate that bitumen is becoming universally scarce. Production restrictions in one region may coincide with improved availability elsewhere, while seasonal construction demand can ease shortages that were particularly severe during the summer.
What has changed is the range of risks that buyers must consider when assessing whether a supply arrangement is dependable. Refinery feedstocks, international sanctions, marine transport, terminal capacity and product compatibility are now prominent considerations alongside the familiar questions of grade, quantity and price.
Governments continue to commit substantial investment to highway construction and maintenance, with projects requiring dependable access to bitumen throughout their delivery programmes. Contractors undertaking that work cannot always align procurement commitments with the timescales of the infrastructure contracts they have accepted.
The international bitumen trade will continue to adapt as refiners and traders respond to changing conditions. For the construction industry, the immediate challenge is securing reliable supplies while managing the financial exposure created when material availability and pricing can change long before a road project is completed.
Key Industry Questions
- Why has global bitumen supply become more unpredictable? Geopolitical conflict, sanctions, refinery maintenance and shortages of suitable heavy crude have disrupted established production and trading arrangements. Availability also depends on seasonal demand, transportation capacity and the ability of refineries to manufacture required grades.
- How has the conflict involving Iran affected bitumen production? Disruption to Gulf shipping has restricted the availability of some Middle Eastern crude supplies. Refineries dependent on suitable heavy feedstocks may produce less bitumen when forced to process alternative grades, even if they maintain substantial overall crude throughput.
- Why can’t refineries simply produce more bitumen when demand increases? Bitumen yield depends on crude oil composition, refinery configuration and operating conditions. Increasing output may require suitable heavy feedstocks or changes to refinery operations, while refiners must also balance production against demand for other petroleum products.
- Is Europe becoming more dependent on imported bitumen? Europe already relies on a combination of domestic refinery production and international imports. Recent refinery outages have demonstrated the importance of alternative sources, but establishing a long-term increase in import dependence requires consistent production and trade data over several years.
- Is the United States exporting bitumen to Europe? Yes. World Bank data records approximately 15,269 tonnes imported by the EU from the United States during 2025, with the UK separately importing around 22,979 tonnes. These figures confirm established trade flows but do not establish how volumes changed during 2026.
- Are long-term bitumen supply contracts disappearing? There is insufficient evidence to establish an industry-wide move away from long-term contracts. Term agreements remain important, although volatility can affect pricing formulas, available volumes and the willingness of suppliers to make firm delivery commitments.
- Can contractors substitute bitumen from another country? Potentially, provided the replacement material meets the relevant technical specifications and project requirements. Equivalent grade descriptions do not always guarantee identical performance, and additional testing or approval may be required.
- How can infrastructure contractors reduce supply risks? Practical measures include supplier diversification, verification of refinery and product origin, appropriate price-adjustment clauses, independent quality testing and access to alternative logistics arrangements. Additional storage may be justified where the project scale and interruption risk support the cost.
Strategic Takeaways
- Refinery feedstocks are a critical supply constraint. Access to crude oil does not guarantee suitable bitumen production, particularly when refiners must substitute lighter grades for established heavy feedstocks.
- European supply chains remain exposed to regional refinery failures. The French and German disruptions demonstrated how production problems can affect neighbouring markets through shared distribution networks.
- International sourcing options are expanding geographically. Existing transatlantic trade and alternative regional supply arrangements provide buyers with additional options, subject to freight economics and technical compatibility.
- Term contracts and spot purchases carry different risks. Forward agreements may improve volume security, while spot markets provide flexibility but can expose buyers to sudden changes in price and availability.
- Infrastructure procurement requires greater attention to supply continuity. Contractors must balance material costs against delivery reliability, technical compliance and the consequences of interrupted asphalt production.